$13.55 a share, in cash. That is the price Canadian Natural Resources agreed on Nov. 16 to pay for Advantage Energy: about $2.255 billion for the equity on a fully diluted basis, and about $2.53 billion once Advantage’s net debt and convertible debentures are counted.
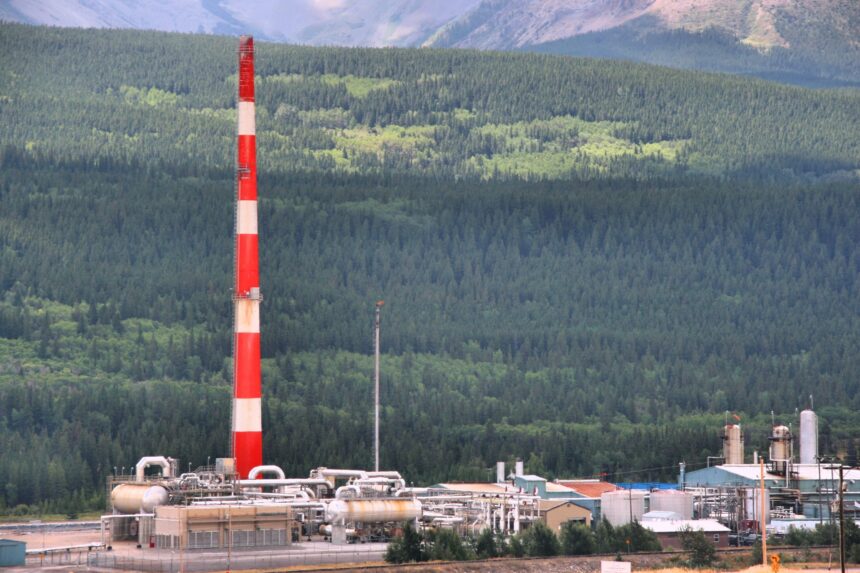
The production sits next to Canadian Natural’s own operations in the Grande Prairie area of northwest Alberta. The deal still needs Advantage shareholders, a Competition Act review and the Court of King’s Bench of Alberta, and both companies are aiming to close in the first quarter of 2027.
Key facts
- Canadian Natural Resources Limited agreed on Nov. 16, 2026 to acquire Advantage Energy Ltd. for $13.55 per share in cash, about $2.255 billion in equity and $2.53 billion including net debt and convertible debentures, according to Canadian Natural.
- Canadian Natural describes the acquired production as about 79,000 barrels of oil equivalent per day and values the deal at about $32,000 per flowing barrel of oil equivalent per day.
- Advantage Energy reported average production of about 87,000 barrels of oil equivalent per day in the third quarter of 2026, according to its Nov. 16, 2026 release.
- Advantage Energy expects to hold the shareholder vote on the deal at a special meeting in January 2027, and the transaction also requires Competition Act approval and approval of the Court of King’s Bench of Alberta.
The two companies count the production differently
Canadian Natural’s release says the deal adds about 79,000 barrels of oil equivalent a day and prices it at about $32,000 per flowing barrel. Advantage’s own release reports third-quarter production of about 87,000. Neither explains the difference. One figure is the seller’s quarterly average. The other is the buyer’s count of what it is acquiring, and it is the number the buyer’s valuation rests on.
The gap matters to the price. By Alberta Tribune’s arithmetic, $2.53 billion spread over 87,000 barrels a day works out to about $29,100 per flowing barrel. Over 79,000, it is the $32,000 Canadian Natural quotes. A reader comparing this deal with others should use the buyer’s figure and know which production base sits under it.
Advantage shareholders get a 25% premium and a unanimous board
Advantage says the price is a 25% premium to its Nov. 13 closing price on the Toronto Stock Exchange and to its 30-day volume-weighted average, and above any price its shares have traded at in 18 years. A special committee ran the review, Peters & Co. and Scotiabank gave fairness opinions, and every director and executive officer has signed a support agreement to vote in favour. The information circular is expected in December and the vote in January. John Festival, the board chair, is also serving as interim chief executive.
Canadian Natural is paying from cash and credit
The buyer is funding the deal from cash on hand and its existing bank credit facilities. The difference between the equity price and the total value is about $275 million by Alberta Tribune’s arithmetic, which covers Advantage’s net debt and its $143.75 million of 5% convertible debentures due June 30, 2029. Under the agreement, Canadian Natural will satisfy the debentures, including their change-of-control terms. It also says it will keep its policy of targeting 100% of free cash flow for share buybacks, subject to market conditions.
What it gets for the money is processing and inventory as much as current output. Advantage owns the 425 million cubic feet a day Glacier Gas Plant and the newly commissioned 75 million cubic feet a day Progress Gas Plant, and reports more than 2,200 drilling locations: 309 proved, 80 probable and 1,811 unbooked. By Alberta Tribune’s arithmetic, about 82% of that inventory is unbooked. Alberta gas has new outlets in the works, including the Yellowhead Pipeline, which broke ground at $2.9 billion, and the work behind it depends on an energy workforce facing a wave of retirements.
The deal works only if the neighbouring assets cost less to run together
Canadian Natural president Scott Stauth framed the logic as “synergies of scale to further improve on area efficiencies.” If those savings show up in lower costs per barrel across the Grande Prairie area, the company has bought plants and drilling inventory next door at about $32,000 per flowing barrel by its own measure. If they do not, it has paid a 25% premium for production in an area where it already operates, funded partly on credit, while promising its free cash flow to buybacks. Export routes for Alberta’s light oil matter too, as the debate over Prince Rupert crude by rail showed.
The first test is Advantage’s special meeting in January 2027. The second is the Competition Bureau review. After closing, the number to watch is the natural gas operating cost per unit in Canadian Natural’s 2027 quarterly reports, because that is where the promised efficiencies either appear or do not.